Business Funding Insights
Expert advice on business loans, financial strategy, real estate, and building lasting wealth.

Stop Chasing Debt: Why Your Growth Strategy Needs a Funding Architecture, Not Just a Loan
You have spent years building a reputation, hiring the right people, and solving problems that keep your competitors up at night. Yet, when you look at your growth roadmap, you feel a familiar, tightening sensation in your chest. The conventional wisdom says you need a traditional bank loan to scale. I am here to tell you that this mindset is precisely what is keeping you small. Most business owners treat funding like a utility bill—something to be endured—when it should be treated as an architectural asset. If you keep asking for permission from institutions that do not understand your business model, you will never gain the leverage you actually deserve. It is time to look at creative, non-traditional funding structures that turn your balance sheet into a powerhouse rather than a leash.
The Hidden Multiplier: Unlocking Commercial Property Equity Beyond the Surface
You have spent years treating your commercial property as a static asset, assuming that time alone would dictate your equity position. You are wrong. While you wait for market appreciation to save you, you are sitting on a goldmine of unrealized potential that requires no new construction and no massive capital injections. Most business owners look at their real estate as a shell that houses their operations, but the truly elite see it as a programmable financial instrument. The difference between a property that barely covers its debt service and one that acts as a powerhouse for your balance sheet isn't luck—it is a series of deliberate, tactical pivots. It is time to stop being a passive landlord of your own business and start engineering the value that your equity deserves.

The Secret Loan Strategy: How One Debt Can Unlock Bigger Opportunities
You've been told loans are a one-and-done deal, a necessary evil to get by. But what if that's fundamentally wrong? What if the loan you secure today isn't just a solution for a current problem, but a carefully placed stepping stone towards something far more significant? Imagine leveraging a smaller, more accessible loan not just to bridge a gap, but to actively build the financial profile and credibility needed to qualify for the game-changing funding your business truly deserves. This isn't about taking on more debt; it's about strategic debt deployment. Are you ready to rethink your entire approach to business financing?

Stop Writing Business Plans for Lenders: Start Writing for Your Survival
You think your business plan is a hurdle to clear for a loan officer. You are wrong. If your business plan is merely a collection of projections designed to satisfy a banker’s spreadsheet, you are wasting your most valuable asset: your own strategic clarity. Most founders view funding documents as a necessary evil, a stack of paper to be endured. This is why so many promising ventures stall when they hit their first real market friction. When you write a plan to please someone else, you are effectively lying to yourself about your own risks. Today, we strip away the corporate theater. We are going to build a narrative that doesn't just unlock capital—it gives you the blueprint to survive the hardest years of your business life.

The Strategic Edge: Stop Treating Your Business Line of Credit Like an Emergency Fund
Most business owners view a line of credit as a safety net—a financial parachute for when the engine stalls. That is a fundamental mistake that is silently bleeding your growth dry. If you are using your revolving credit only to cover payroll during a bad month or to patch up cash flow leaks, you are not leveraging capital; you are simply managing survival. A line of credit is not meant to be a crutch. It is the most powerful, agile tool in your financial arsenal, designed to scale operations, seize fleeting market opportunities, and negotiate better terms with suppliers. When you shift your perspective from 'safety net' to 'growth accelerator,' you stop playing defense. Today, we strip away the conventional wisdom and show you how to weaponize your access to capital.
Merchant Cash Advances: The Funding Tool That Can Save Your Business or Sink It
You have been staring at your bank balance for twenty minutes. The rent is due, a key supplier just demanded payment upfront, and your primary customer account is sitting on a sixty-day delay. You know the traditional bank route will take weeks, and you simply do not have that kind of time. This is the moment where desperation usually dictates strategy, leading many owners to jump blindly into a Merchant Cash Advance (MCA). But what if you stopped viewing it as a lifeline and started treating it like a precision surgical tool? In this guide, we dismantle the myths surrounding MCAs, identify exactly when they serve as a strategic bridge, and provide the blueprint to ensure you remain in control of your cash flow rather than being crushed by it.

The Personal Guarantee Trap: Why Your Signature Might Be Your Biggest Business Liability
You have spent years pouring your soul into your business. Every late night, every missed weekend, every sacrifice—it was all for the dream of freedom. But then comes the loan application, and there it sits on the final page: a line for your personal guarantee. You hesitate. You wonder if this is just standard protocol or if you are unknowingly putting your personal survival on the line for a corporate entity. The truth is, that signature acts as a bridge between your company's potential and your personal peace of mind. Many business owners rush through this phase to secure the capital they need to survive today, without realizing how it might jeopardize their stability tomorrow. It is time to stop viewing the personal guarantee as a formality and start seeing it as a strategic risk.
Why Your Best Equipment Purchase Is Actually a Debt Strategy, Not an Asset Buy
You have been taught that buying equipment is a cost of doing business, a necessary evil that drains your cash reserves just to keep the lights on. That is the quickest way to kill your growth. Most business owners look at a piece of machinery and see a price tag; they miss the silent engine of profitability hiding behind the financing contract. When you stop viewing equipment as an expense to be paid off and start treating it as a leverage tool for cash flow velocity, the rules of the game shift entirely. You aren't just buying a tool; you are buying the ability to outpace your competition while keeping your liquidity untouched. It is time to stop sacrificing your runway for hardware and start using equipment financing to build a war chest for the future.
Stop Treating Debt Like a Death Sentence: The Strategic Art of Revenue-Based Financing
You have been taught that debt is a four-letter word. You have been told to bootstrap until you break, or to surrender your equity to a venture capitalist who will watch you like a hawk. But there is a silent third path—a way to fund your ambition without selling your soul or handcuffing your future. Revenue-based financing is not a magic wand, and it is certainly not a loan in the traditional, suffocating sense. It is a surgical tool. When used with precision, it acts as a force multiplier for your cash flow, allowing you to buy growth today with the revenue you are creating tomorrow. If you are tired of the trade-off between control and capital, it is time to stop viewing financing as a burden and start seeing it as your most powerful lever.
The Silent Killers of Your Business Funding Application
You have done the work. You have poured your soul into your vision, yet the bank says no. It is not just frustrating; it feels personal. But here is the raw, uncomfortable truth: most loan rejections have nothing to do with the strength of your idea and everything to do with how you packaged your ambition. You are likely making the same three mistakes that hundreds of business owners make every single day—mistakes that signal instability to lenders even when your business is thriving. We have seen brilliant entrepreneurs derailed by a single missing document or a misinterpreted financial statement. It is time to stop playing the guessing game with your capital. Let us pull back the curtain on why your application is failing and how you can reclaim control of your financial destiny starting today.

Stop Chasing Banks: The Truth About Documentation for Non-Traditional Funding
You have spent countless nights staring at the ceiling, wondering if the bank's rejection letter was the final word on your dream. It feels personal, doesn't it? But here is the brutal reality: the bank's 'no' is rarely about your business potential; it is almost always about your inability to speak their outdated language. You are trying to fit a digital-age, high-velocity business into a paper-based, 1950s approval mold. That is why you feel stuck. When you pivot toward non-traditional funding, the rules of the game change entirely. You do not need a mountain of collateral or a perfect balance sheet; you need clarity, transparency, and a story told through data. Let’s dismantle the myth that funding is reserved only for the flawless and learn what actually moves the needle.
The Hidden Cost of Your Credit Score: How to Stop Paying for Past Mistakes
You have been told your entire business life that your credit score is the ultimate arbiter of your success, but that is only half the truth. You are currently paying a 'growth tax' on every piece of equipment, inventory shipment, and expansion plan because you view credit as a report card rather than a strategic asset. While your peers are obsessing over digits and decimal points, you are ignoring the architectural flaws in how your business profile is actually built. This isn't about being perfect; it's about being intentional. Whether you are bootstrapping your way through a rough patch or scaling toward a million-dollar quarter, your credit profile is the silent partner determining your terms. It is time to stop apologizing for your history and start engineering your future. Let’s pull back the curtain on how elite borrowers actually build their leverage.
Beyond the Bottom Line: What Lenders Really See When They Scrutinize Your Financials
You think your financial statements are just a historical record of what went wrong—or right—last year. You are wrong. To a seasoned lender, your balance sheet is a pulse, a map of your character, and the ultimate predictor of whether your business will survive the next market shift or crumble under the pressure. Most entrepreneurs approach the loan process like a student submitting a term paper, hoping for a passing grade. But the lenders who actually hold the keys to growth aren't grading you on your profit margins alone; they are hunting for the narrative hidden between the lines of your spreadsheets. If you’ve ever wondered why a profitable business gets rejected while a leaner operation gets funded, the secret lies in how you tell your financial story.
Beyond the Bank: Why Your Credit Score is Not the Only Measure of Your Ambition
You have spent countless nights staring at the ceiling, calculating how many more months of growth you could unlock if you just had the right capital. You have been told that if your bank says no, your dream is effectively stalled. This is the biggest lie in modern finance. Your ambition is not tied to a three-digit number on a credit report, yet you are operating as if it is. The truth is that there is an entire ecosystem of non-traditional funding specifically designed for businesses that don't fit the rigid, outdated boxes of traditional banking. It is time to stop apologizing for your reality and start leveraging the right tools for your specific growth stage. You deserve to know how the game is actually played, and more importantly, how to win it on your own terms.
Beyond the Bank: The Invisible Rules of Securing Non-Traditional Funding
You have done everything right. You have followed the standard playbook, kept your margins tight, and poured your soul into your business. Yet, when you walked into the bank, they looked at your spreadsheet as if it were written in a foreign language. The doors slammed shut, not because your business lacks value, but because you are trying to force a square peg into a round hole. You are relying on traditional metrics in a landscape that has shifted entirely beneath your feet. Securing non-traditional funding is not about desperation; it is about demonstrating a different kind of strength. It requires shifting your perspective from asking for help to proving your momentum. Let's dismantle the myths that are holding your business back and unlock the capital that is actually within your reach today.
Stop Feeding the Cash Flow Monster: Why Sustainable Funding Isn't About the Next Loan
You are staring at your bank balance, waiting for the ‘ding’ of a client payment, while secretly wondering if this is how your business is supposed to feel: a permanent, white-knuckled sprint. We have been conditioned to treat funding like a life raft, something we grab only when the ship is already taking on water. But what if the secret to real growth isn't finding more capital, but fundamentally changing your relationship with how that capital behaves? If you are tired of playing a game where the rules are designed for you to fail, it is time to stop chasing liquidity and start building a self-sustaining engine. The truth is, most business owners are one bad month away from exhaustion, not because they lack skill, but because they are trapped in a short-term funding cycle that keeps them perpetually small.

Stop Feeding the Lender: How to Fix Your Cash Flow Before You Borrow
Most business owners believe the lender is the gatekeeper to their success. You are wrong. The real gatekeeper isn't the bank manager or the algorithm—it is the messy, leaking reality of your current cash flow. Every day you wait to fix your margins before applying for a loan, you are effectively paying a premium for your own lack of preparation. You feel the weight of every unpaid invoice and the anxiety of wondering if the rent is covered. But what if you stopped looking at a loan as your rescue plan and started treating it as a performance multiplier? Today, we are going to dismantle the misconception that you need a loan to fix a broken process. It is time to stop reacting to your bank balance and start commanding it, so when you do walk into that lender’s office, you do it on your terms.
The Debt Balancing Act: How to Stack Funding Without Burning Out
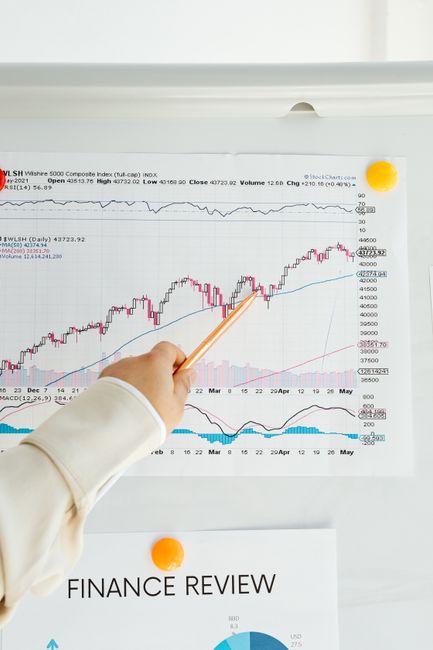
You aren't failing because you have multiple loans; you're failing because you're treating them like a single, suffocating weight instead of a surgical toolkit. Most business owners view debt as a moral failing or a sign of impending collapse. They are wrong. When used with clinical precision, stacking diverse funding products is the fastest way to scale, yet it is also the quickest way to insolvency if your strategy is 'hope for the best.' Managing multiple streams of capital requires a shift from passive repayment to active treasury management. You are the architect of your own balance sheet. It is time to stop reacting to your bills and start commanding them. If you are feeling the pressure of multiple payment dates, this guide is your roadmap to regaining control.
The Credit Trap: Why Your Best Path to Funding Isn't a Bank Loan
You have been told the same lie for years: you need to prove your creditworthiness to a bank before you can build your business. But here is the brutal truth—if you wait for a traditional lender to give you the green light, your competition will have already lapped you. The obsession with personal FICO scores is a relic of a bygone era, and for many entrepreneurs, it is the invisible ceiling limiting their growth. You are stuck playing a game where the rules were written by people who do not understand the grit, the late nights, or the sheer velocity of modern commerce. It is time to stop asking for permission and start building your financial independence from the ground up. Let's dismantle the myth of the 'perfect' credit profile.
Why Your Debt-to-Income Ratio is the Silent Partner You Cannot Ignore
You have poured your soul into your business. You have the vision, the drive, and the sleepless nights to prove it. Yet, when you sit across from a lender, you are reduced to a single number that feels like a verdict on your worth. The debt-to-income (DTI) ratio is the most misunderstood gatekeeper in the world of business finance. Many founders believe it is simply a math problem, but in reality, it is a narrative—a story about your risk, your discipline, and your future. If you think DTI is just a barrier to capital, you are missing the opportunity to use it as a compass for your company's growth. Stop viewing it as a cage and start mastering it as your ultimate leverage.
Stop Chasing Cash: Why Your Next Capital Move Is About Relationships, Not Spreadsheets
You have spent years treating your lender like an ATM: you show up, punch in your numbers, hope for approval, and walk away feeling lucky to have escaped with the funds. But here is the brutal truth that most entrepreneurs never realize: if you are only interacting with your lender when you need a check, you have already lost the game. Business funding is not about filling out forms; it is about building a bridge that supports you long before the crisis hits. Your financial partner should be an asset, not an adversary. In this guide, we strip away the traditional myths of borrowing and show you how to move from a transactional applicant to a preferred client. It is time to stop begging for capital and start commanding it with a strategy that lasts.
Escaping the Funding Trap: When to Graduate to Traditional Business Lending
You started with high-cost bridge funding because it was the only door left open, and it saved your business from a premature grave. But here is the brutal truth: that same lifeline is now a chain holding you back from real growth. Many founders get trapped in a cycle of immediate-need capital, terrified that the 'traditional' world won't have them. They are wrong. The transition from non-traditional to traditional funding isn't just about lower interest rates; it is about reclaiming the sovereignty of your balance sheet. In this guide, we strip away the fear of the bank application process and show you the exact markers of a business ready to move from survival mode to scaling mode. Your business has matured, and it is time your capital structure finally caught up.

Why Your Business Equity is More Than Just a Safety Net
You have spent years pouring your soul into your business, treating every dollar of equity like a sacred treasure meant to be guarded at all costs. But what if that caution is exactly what is keeping you trapped in the status quo? Most business owners view equity as a rainy-day fund or an exit prize, failing to realize that dormant equity is actually a liability in disguise. When your capital sits stagnant while your industry evolves, you are losing more than just potential interest; you are losing your relevance. Leveraging equity for expansion isn't about gambling with your hard-earned asset—it is about weaponizing your success to outpace the competition. It is time to stop viewing your equity as a trophy and start treating it as the most powerful engine for growth you currently own.
Stop Chasing Cash Flow: The Hidden Mechanics of Forced Equity in Commercial Real Estate
You have been told that property appreciation is something that happens to you, a byproduct of time and market trends. That is a lie that keeps thousands of business owners trapped in mediocrity. While the market wanders, the most successful investors aren't waiting for the tide to rise—they are dredging the harbor themselves. You do not need to wait for a booming economy to unlock the true value of your commercial asset. There is a precise, surgical way to manufacture equity, turning stagnant walls into a dynamic financial engine. If you feel like you are working harder for less, it is because you are playing a passive game in an active market. It is time to stop being a spectator of your own net worth. Here is how you force value today.
Beyond the Bank: Why Your Growth Strategy is Likely Failing You
You have been told that the holy grail of business growth is a traditional bank loan. You have spent weeks gathering tax returns, perfecting your balance sheet, and praying to the gods of underwriting, only to be met with a cold, impersonal rejection. Here is the uncomfortable truth: you are not being turned down because your business isn't valuable; you are being turned down because you are trying to fit a square peg into a round hole. Traditional banking was designed for a world that no longer exists. If you continue to rely on antiquated funding models, you are not just limiting your capital—you are actively handcuffing your potential. It is time to stop playing the beggar at the bank’s door and start architecting a funding structure that actually aligns with your ambition.
The Funding Ladder: Why Your First Loan Should Be a Strategic Asset, Not Just Cash
Most business owners treat debt like a fire extinguisher: they only reach for it when the walls are already smoldering. This reactive mindset is exactly what keeps you trapped in a cycle of high-interest, short-term survival funding. You aren't just looking for cash to bridge a payroll gap; you are looking for a key to unlock your next level of growth. What if I told you that your current loan application is actually a dress rehearsal for the major capital infusion you will need two years from now? The secret isn't finding the cheapest money; it is finding the right money that proves your viability to future institutional lenders. Stop playing for the immediate win and start building a credit narrative that makes banks compete for your business. It is time to learn how to position your company for the long game.
The Silent Killer of Growth: Why Your Business Line of Credit Is Failing You
Most business owners treat a line of credit like a safety net. That is a dangerous mistake that is likely strangling your cash flow while you sleep. You probably view your line of credit as emergency backup capital for when things go wrong. But if you are using it to plug holes, you are playing a losing game of catch-up. True growth doesn't come from surviving; it comes from strategic deployment. If you find yourself constantly drawing down your limit just to cover payroll or mundane operating expenses, you are not managing capital—you are drowning in it. In this guide, we are going to tear down the myths of debt management and show you how to transform your line of credit from a crutch into a weapon for market dominance.
Why Most Business Plans Fail to Get Funded (And How Yours Can Win)
You have poured your soul, your savings, and your sleep into this business, yet when you sit across from a lender, you feel like you are speaking a foreign language. The cold, hard truth is that most business plans are treated as administrative paperwork rather than the survival documents they actually are. You are not just asking for money; you are asking for a partner to bet on your vision. If your plan is a generic collection of projections and fluff, you have already lost the room. Today, we are going to strip away the vanity metrics and the corporate jargon to build a narrative that forces a lender to see what you see. It is time to stop apologizing for your ambition and start proving your math. Your future is waiting.
The Personal Guarantee Trap: What Lenders Won’t Tell You About Your Assets
You have spent years pouring your soul, your savings, and your sleep into your business. Then, you sit down to sign a funding agreement, and there it is: a small, unassuming paragraph that puts your home, your car, and your personal savings on the line. It is the personal guarantee—a legal tether that connects your professional ambition directly to your personal survival. Most business owners sign it without a second thought because they are blinded by the urgent need for growth capital. But understanding what you are actually trading away is not just good business sense; it is an act of survival. In this guide, we strip away the legal jargon and the pressure tactics to show you exactly what a personal guarantee means for your future and how you can navigate it with your eyes wide open.
Beyond the Debt Trap: Mastering Revenue-Based Financing for Sustainable Growth
You have been told that debt is a necessary evil—a burden to be carried until your balance sheet looks healthy enough for a traditional bank. But what if the way you pay for your growth is actually holding your growth back? Revenue-based financing is frequently misunderstood as a last resort, yet for the most agile businesses, it is a high-octane engine for expansion. The reality is that your cash flow should dictate your debt, not the other way around. If you are tired of rigid monthly payments that crush your momentum during slow seasons or strangle your expansion during rapid growth, you need a different perspective. Today, we are dismantling the fear surrounding flexible capital and showing you how to turn your revenue streams into a surgical tool for scaling.

Why Your Best Equipment Purchase Is Not What You Think
You have been told that debt is a trap. You have been told to save until you can afford to pay cash for every piece of machinery, vehicle, or software suite your business needs. It is time to shatter that myth. By waiting until you have the liquid capital to buy equipment outright, you are not being fiscally responsible; you are actively strangling your own growth. Cash is the lifeblood of your operation, and locking it away in depreciating assets is one of the fastest ways to stall your momentum. When you leverage equipment financing correctly, you aren't just buying a tool; you are buying time, capacity, and a competitive advantage that pays for itself. Let’s look at how to stop financing your business with your own survival capital and start using smarter structures to scale.
The Brutal Truth About Merchant Cash Advances: A Strategic Tool, Not a Last Resort
Most business owners treat a Merchant Cash Advance like a siren song—a dangerous temptation they hope to avoid at all costs. But here is the secret that seasoned entrepreneurs know: a tool is only as dangerous as the hand that wields it. You are likely drowning in advice about how these advances are the 'end of the road' or a financial death trap. I am here to tell you that this is fundamentally wrong. When used with surgical precision, an advance isn't a sign of weakness; it is a tactical lever used to capture fleeting opportunities that traditional banks are too slow to see. If you have ever felt like your growth is being held hostage by rigid lending cycles, it is time to look at capital differently. Let’s dissect the real power of liquidity.
The Silent Loan Killers: Why Your Loan Application is Probably Already Dead on Arrival
You have spent weeks perfecting your business plan, scrubbing your financials, and crafting the perfect pitch. You hit submit, heart pounding with anticipation, only to be met with the deafening silence of a rejection email—or worse, total ghosting. It feels personal, doesn't it? It feels like the system is rigged against you. But here is the hard truth: lenders aren't rejecting you because they don't like your vision. They are rejecting you because you are making the exact same structural errors that thousands of other brilliant entrepreneurs make every single day. You are focusing on the 'why' of your business when the lender only cares about the 'how' of your survival. Today, we strip away the veneer of the application process to reveal the hidden mistakes that are killing your funding chances before you even begin.

The Paperwork Paradox: Why Your Financial Perfection Might Actually Be Hurting Your Funding Chances
You think the secret to non-traditional funding is a flawless credit score and a mountain of perfectly organized spreadsheets. You are wrong. In fact, most business owners lose their chance at capital not because they are financially weak, but because they over-prepare the wrong documents while ignoring the heartbeat of their operation. You have been told that lenders want a polished facade, but the truth is far more raw and interesting. When you step outside the world of traditional banks, the rules of the game change entirely. It is not about looking perfect; it is about looking real. Stop burying yourself in irrelevant tax forms and start gathering the narrative proof that shows your business is a living, breathing engine. Let’s strip away the noise and get to the documents that actually matter to your survival.
The Silent Engine: Why Your Business Credit Score is Costing You More Than You Think
You have spent countless late nights refining your product, managing your team, and grinding through the inevitable friction of entrepreneurship. You think your success is measured by your revenue, but there is a silent engine running in the background of your operation that dictates your ceiling. It is your business credit profile. Most owners treat this like a passive shadow—something that just exists—but that apathy is bleeding your bottom line dry. Every percentage point in an interest rate or every denied credit application is not just bad luck; it is a direct consequence of a credit strategy you have ignored. If you are tired of playing by the rules of lenders who do not understand your vision, it is time to stop playing defense and start architecting your financial reputation.
The Silent Language of Your Financial Statements: What Lenders Actually See
You think your financial statements are just a tally of what you spent and earned, but to a lender, they are a psychological profile of your character under pressure. Every entry tells a story, and most business owners are accidentally writing a horror story when they intend to write an epic. You’ve worked too hard to let a messy spreadsheet be the reason your expansion dream dies at the desk of a credit officer. The reality is that lenders aren't just looking for a high profit margin; they are looking for the 'why' behind the numbers. In this post, we strip away the accounting jargon to reveal exactly what professionals look for when they review your books, and how you can reclaim control over the narrative your business tells.
Beyond the Bank: Why Your Credit Score is Not the Only Measure of Your Business Worth
You have done the work. You have poured your life, your sleep, and your savings into your vision. Yet, when you walk into a traditional bank, they treat you like a risk on a spreadsheet rather than a pioneer building the future. It is a soul-crushing experience that leaves many founders questioning their own potential. But here is the hard truth that banks do not want you to know: your credit score is a lagging indicator of a past life, not a reflection of your future success. There are entire ecosystems of capital designed for high-potential businesses that operate outside the rigid, outdated metrics of traditional lending. You are not stuck. You are simply looking at the wrong map. It is time to stop playing by rules that were never meant to help you win.

The Cash Flow Mirage: Stop Chasing Loans Until You Master Your Velocity
You have been told that a bank loan is the fuel your business needs to blast off. But what if you are trying to pour premium fuel into a tank with a jagged, gaping hole? Most business owners make the fatal mistake of seeking capital to fix a cash flow problem, not realizing that external funding only accelerates the speed at which you fail if your internal metrics remain broken. You feel the anxiety of payroll day creeping up, the silent dread of unpaid invoices, and the pressure to find a quick injection of cash. Stop. Take a breath. Before you prepare a single application, you need to understand that lenders do not reward ambition; they reward predictability. Let us talk about how to stop leaking cash and start building a fortress.
The Funding Paradox: Why Being 'Perfect' on Paper Might Actually Kill Your Chances
You have done everything the traditional banking brochures told you to do. You kept your debt low, your credit score high, and your books spotless. Yet, when you walked into the branch, the door stayed locked. If you are sitting there wondering why your business success hasn't translated into capital, it is time to face a cold, hard truth: the system is not designed to support your growth; it is designed to manage its own risk. You are not a failure because the bank said no. You are simply playing a game with the wrong rules. To access non-traditional funding, you must stop acting like a candidate for a mortgage and start behaving like a business that knows its own velocity. Let’s dismantle the myths standing between you and your next phase of growth.

Stop Chasing Cash: Why Sustainable Funding is About Architecture, Not Just Capital
You aren't failing because you can't find money; you're failing because you're treating fuel like a finish line. Every day, I talk to founders who are brilliant at their craft but trapped in a perpetual cycle of desperation, sprinting from one high-interest bridge loan to the next, hoping for a miracle that never comes. You think your biggest problem is cash flow, but your actual problem is the lack of a financial foundation. Stop viewing funding as a bandage for your current crisis and start viewing it as an infrastructure project. Real wealth isn't built on the adrenaline of a quick injection of capital; it is built on the cold, hard logic of sustainable leverage. Today, we strip away the myths of 'easy money' and rebuild your strategy from the ground up.
The Debt Juggling Act: Why Multiple Loan Products Could Be Your Greatest Asset or Your Silent Killer
You started your business to find freedom, yet here you are, trapped in a spreadsheet of compounding interest and payment dates that feel like a ticking clock. It is the secret shame of the entrepreneur: holding a line of credit, an equipment lease, and a term loan simultaneously, and praying the cash flow holds for one more month. Most experts will tell you that multiple loans are a sign of failure, but the truth is far more nuanced. You are not failing because you have debt; you are at risk because you lack a tactical architecture for managing it. This isn't about paying off debt; it is about leveraging your capital stack to scale while keeping the wolves from the door. Let’s strip away the fear and look at the math of growth.

The Credit Paradox: Why Your Best Path to Funding Isn’t a Traditional Loan
You have been told the same lie for years: you need credit to get money, and you need money to get credit. It is a suffocating cycle that keeps thousands of brilliant entrepreneurs trapped in the 'startup struggle' indefinitely. You have likely spent months chasing traditional bank approvals only to be met with a cold, automated denial. But what if the conventional wisdom is exactly what is holding you back? There is a secret pathway that successful, battle-hardened business owners use to bypass the gatekeepers of traditional lending. By leveraging non-traditional funding instruments, you are not just getting capital; you are architecting a financial reputation that banks will eventually fight to court. It is time to stop playing by their rules and start building your business on your own terms.
The DTI Trap: Why Your Business Math Might Be Killing Your Funding Chances
You have done everything right. You wake up before the sun, you pour your soul into every invoice, and you treat your business like your firstborn child. Yet, when you sit across from a lender, they look at your numbers, shake their head, and offer a polite rejection. It feels personal, doesn't it? It feels like they are judging your worthiness based on a sterile spreadsheet. The truth is much colder and far more fixable: you are likely falling into the Debt-to-Income (DTI) trap. Most entrepreneurs think their profit margins are the only currency that matters, but lenders are playing a different game entirely. They are looking for the 'stress point' of your financial health. Today, we peel back the curtain on the metric that dictates your future.
Why Your Best Lender Isn't the One Who Said Yes First
You have been taught that getting a 'yes' from a lender is the finish line. You celebrate the capital in your account, pay the installments, and assume you have mastered the game. But what if I told you that treating your lender like a utility provider is the single greatest mistake holding back your long-term scalability? The most successful businesses I have worked with do not view their lenders as transaction machines; they view them as strategic anchors in a volatile market. Most entrepreneurs spend their time chasing the next deal, but the ones who truly win are the ones who spend their time curating a capital ecosystem before they even need the money. If you want to survive the next downturn and thrive in the inevitable growth spurts, you need to change your relationship with debt starting today.
The Graduation Strategy: Evolving from Alternative Funding to Traditional Lending
You started with alternative funding because the banks wouldn't give you the time of day. You did what you had to do to survive, to keep the payroll checks from bouncing, and to scale when opportunity knocked. But here is the truth nobody tells you: your business has outgrown the emergency room, and it is time to move into a sustainable ecosystem. Staying in the world of high-cost, short-term capital when your business is ready for prime-time institutional lending isn't just a strategy; it is a tax on your future profit margins. In this guide, we are pulling back the curtain on exactly how to position your business to attract traditional lenders, proving that you have the stability and the vision to deserve lower rates and longer terms.
Trading Ownership for Growth: The Brutal Truth About Equity Financing
You have built your business from a whisper to a roar. You know every corner of your P&L, every headache, and every triumph. But now, you are standing at a crossroads. You need fuel to scale, and the world is telling you that selling a piece of your equity is the only way to play the game. They are wrong. Most founders rush into equity agreements because they are blinded by the shiny promise of a cash injection, only to realize too late that they have signed away their autonomy for a seat at their own table. Before you dilute your legacy, you need to understand the hidden costs of capital and whether your business is actually ready to invite partners into the fold. Let’s strip away the corporate polish and look at the real mechanics of growth.
Stop Chasing Cash Flow: The Hidden Strategy to Force Equity in Your Commercial Property
You have been told that the only way to increase your commercial property value is to wait for the market to swing in your favor. You check the Zillow estimates, you watch the local interest rates, and you hope that time alone will do the heavy lifting. But while you wait for external forces to act, you are missing the most powerful lever in commercial real estate: the ability to force appreciation regardless of what the economy is doing. The truth is, your property is not just a building; it is a math equation. If you understand the variables that determine its valuation, you can stop being a spectator to your own net worth and start being the architect of it. It is time to move past passive ownership and start mining for the equity hidden right under your roof.

Beyond the Bank: Why Your Growth Strategy Might Be Hiding in Plain Sight
You have done the hard part. You built a product people crave, you found a team that shares your obsession, and you have survived the grueling early years of thin margins and late nights. Yet, here you are, hitting a wall that feels less like a market shift and more like a lack of fuel. Most owners look at their P&L and assume the bank is the only gatekeeper to their next phase of growth. That is your first mistake. Conventional wisdom suggests that if you cannot get a traditional loan, you are not ready to scale. I am here to tell you that this mindset is not only wrong, it is actively suffocating your potential. The most innovative businesses are not just borrowing money; they are engineering capital structures that protect their equity while fueling their momentum.
The Stepping Stone Strategy: How to Use Bridge Financing to Unlock Better Capital
You have likely been told that you need to be perfect to get the perfect loan. The truth? If your business is waiting for the 'perfect' balance sheet to apply for institutional funding, you are likely already losing the race. Business finance is not a static gate you pass through; it is a ladder you climb. Many owners get trapped by the misconception that they must hold out for the lowest interest rate, missing the reality that cost is often irrelevant if the opportunity cost is higher. By viewing your first, smaller, more accessible loan as a tactical asset rather than a final destination, you can engineer the very metrics that future lenders crave. Stop waiting for permission from the bank. Start building the story they cannot say no to.
Stop Using Your Line of Credit Like a Life Raft
You think your business line of credit is a safety net, don't you? A reserve to catch you when the cash flow dips or a client is late on an invoice. If you treat it like an emergency backup, you are fundamentally misusing one of the most potent growth engines available to you. I have watched hundreds of founders fall into the trap of 'reactive borrowing,' essentially paying for the privilege of keeping their heads just above water. But a line of credit isn't meant for survival; it is designed for velocity. In this post, we are going to dismantle the common myths surrounding credit and look at how high-performing business owners use these tools to manufacture their own luck and dominate their markets before their competition even knows what hit them.